
Pexels | Matheus Bertelli | ChatGPT’s Best Finance Advice—And What Experts Think About It
Artificial intelligence is stepping into areas once reserved for financial professionals. From creating budgets to handling investments, more Canadians now rely on AI tools for money management. A 2024 Bank of Montreal survey revealed that one in three Canadians uses AI for personal finance decisions, ranging from setting up household spending plans to improving overall financial literacy.
But how does the advice from ChatGPT compare with insights from certified financial planners and investment specialists? Common financial questions were posed to ChatGPT, followed by expert evaluation. The results reveal where AI gets it right and where human guidance still matters.
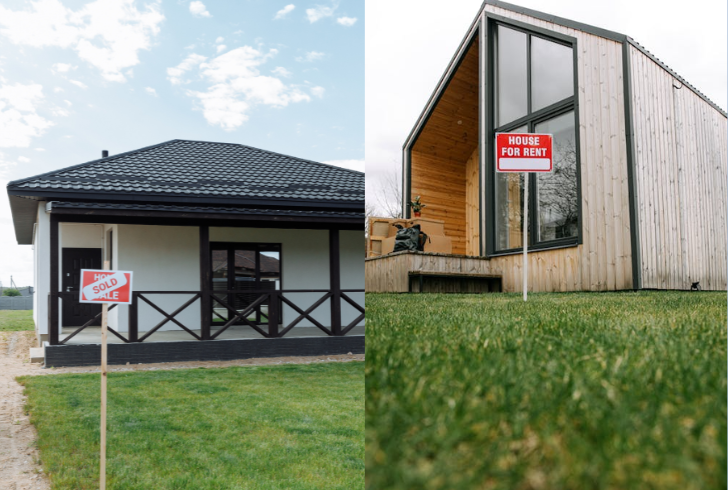
Buying or Renting a Home in Canada
ChatGPT’s Take
Buying is ideal when stable finances, sufficient savings for a down payment, and long-term settlement plans exist. Renting suits those valuing flexibility, avoiding maintenance, or managing limited upfront costs. In areas like as Vancouver or Toronto, renting may even be more financially advantageous in the short run.
Expert Insight
Anita Bruinsma, financial planner and founder of Clarity Personal Finance, stresses that home buying impacts long-term goals. Owning often limits accessible funds for retirement or education savings. Unexpected costs, from roof repairs to replacing appliances, can create affordability challenges.
Benjamin Felix, portfolio manager at PWL Capital, calls the AI response oversimplified. He notes that five years is rarely enough to offset transaction costs. Ownership works best as a hedge against rising housing costs for those staying long term. Importantly, taxes and the benefit of tax-free growth on principal residences were not mentioned.
Tackling Credit Card Debt
ChatGPT’s Take
Two strategies surfaced—the avalanche method, which pays off the highest-interest balance first, and the snowball method, which focuses on smaller balances for motivation. It also recommended balance-transfer credit cards and debt consolidation loans.
Expert Insight
Natasha Macmillan from Ratehub acknowledges avalanche as the most strategic option but notes the difficulty in avoiding all card use. Since cards cover daily expenses, balance transfers with lower interest can provide breathing room.
Felix points out that while the avalanche method is mathematically optimal, snowball offers psychological wins. Research confirms that clearing small balances first boosts motivation. Educating people about interest trade-offs can improve decision-making.
Desmond Nwaerondu from Sun Life emphasizes using avalanche while helping clients build structured repayment plans.
Protecting Money from Inflation
ChatGPT’s Take
Investing is the best defense. Keep only an emergency fund in savings, and place the rest in stocks, real estate, or index funds. Real return bonds and adjusting budgets were also mentioned.
Expert Insight
Bruinsma warns that the advice sounds too simple. Jumping into investments without a strategy can harm long-term wealth.
Adam Chapman, financial planner, stresses income growth as the first inflation defense. Taxes on investment returns, often overlooked by AI, also influence real returns.
Felix argues against putting all excess cash into risky assets. Real return bonds, while inflation-protected, carry other risks, as seen when Canadian real return bond ETFs dropped nearly 24% between late 2021 and 2023.
Starting the Investment Journey
ChatGPT’s Take
Open a TFSA or RRSP via an online brokerage or robo-advisor. Begin with diversified index funds, automate contributions, and stay consistent. Avoid timing the market.
Expert Insight
Bruinsma says banks and mutual funds can be less intimidating entry points. She cautions against investing without a structured plan. Felix points out account-type recommendations can backfire. Factors such as disability plans, U.S. citizenship, or contribution limits alter strategies.
Macmillan reminds that setting financial goals and understanding risk tolerance should come before account selection.
